
Proof, not promises.
Every case study below is a live deployment in a regulated market, built with licensed institutions under financial authority scrutiny.
Shaamilkar — Pakistan
A licensed NBFC lives on a fully Shariah-compliant, SECP-regulated digital financing platform for traders and SMEs.

 End-to-end LMS/LOS, mobile apps, and real-time management dashboard — automating the full lending lifecycle.
- SECP-compliant cloud infrastructure: AES-256 encryption, VPC-segregated networking, 100% in-country data residency.
- Automated integrations with NADRA, credit bureaus, and banking partners. Facilities from PKR 50,000 to PKR 500,000.
- Shariah-compliant
- SECP-compliant
- Cloud-native
- In-country data residency
- Configuration-driven
- API-first
- SECP-compliant
- In-country data residency
Swich — Pakistan
A Pakistani payments company moves into lending, on a configuration-driven loan management system built to launch new credit products without new code.
- An API-first LMS serves as the system of record for the full lending lifecycle: product and pricing configuration, credit limits, loan booking, repayment schedules, delinquency and ageing.
- It plugs into Swich's existing payments platform, with credit assessment, disbursement and repayment running through integrations and automated reconciliation.
- Built for SECP scrutiny: maker-checker controls, double-entry loan ledger, full audit trail, regulatory and credit bureau reporting, and 100% in-country data residency.
- 6
- Live engagements
- 2
- Regulated markets
- SECP · SAMA
- Regulatory regimes
SLGTrax Logistics — Pakistan
Fintech plugins embedded into a logistics network serving 10% of Pakistan's e-commerce market — digitising cash, streamlining payments, and enabling working capital financing for online brands and shippers.
- A wallet at the core: tailored credit that integrates with how the business already operates, rather than sitting beside it.
- A flywheel rather than a product launch — each interaction deepens engagement, and new products arrive as the SME grows into them.
- Network effects do the scaling: the platform expands with the merchants on it, so reach compounds instead of being bought.
- 10% of e-commerce market
- Embedded wallet
- Working capital financing
- Logistics-native
- Regulatory compliant
- Shariah-compliant
- Scalable
- PKR 14B disbursed
Finja — Pakistan
The core team behind a digital lending and payments business built from the ground up, from first licence to PKR 14B disbursed.
- Disbursed over PKR 14 billion across 300,000+ loans, with 35,000+ borrowers in 35+ cities.
- 98.5% month-over-month collection rate, with non-performing loans held at 1%.
- P2P lending through Finja Invest: PKR 1.5 billion facilitated across 450 investors and 10,000 borrowers.
Open Banking Advisory — Saudi Arabia
Partnered with HCC to advise one of the Kingdom's leading banks on open banking strategy under Vision 2030.
- SME financing infrastructure: near-real-time access via integrations with three of the Kingdom's largest institutions.
- Embedded finance API layer accelerating open banking adoption across banks and fintechs.
- AI-driven credit scoring expands lending access for underserved SMEs.
- Vision 2030
- SAMA-regulated market
- API-led integration
- WhatsApp-native
- Verified contribution
- Regulated rails
- 165,000+ women engaged
CIRCLE Women — Pakistan
Converting informal women's economic activity into a verified, financial-institution-readable identity — at population scale. 165,000+ women engaged. 35,000 trained in digital skills.
- WhatsApp-native engagement layer — fully feature-phone accessible, no app required.
- Verified contribution ledger: tamper-resistant records that build a persistent economic identity.
- KYC-lite onboarding, AML monitoring, and settlement on licensed mobile-money infrastructure.
Partnerships in action
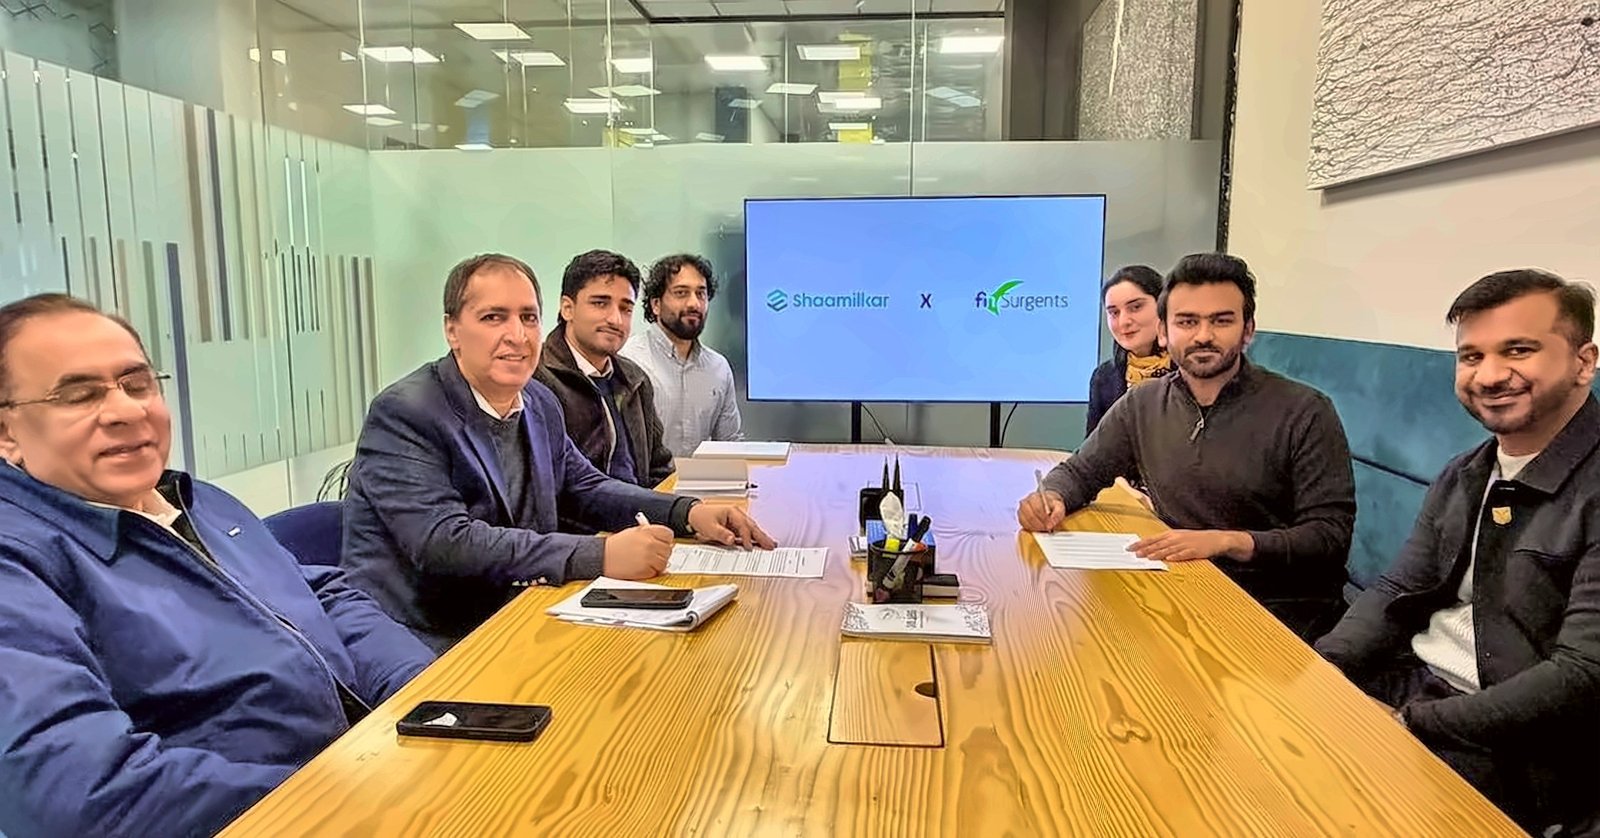
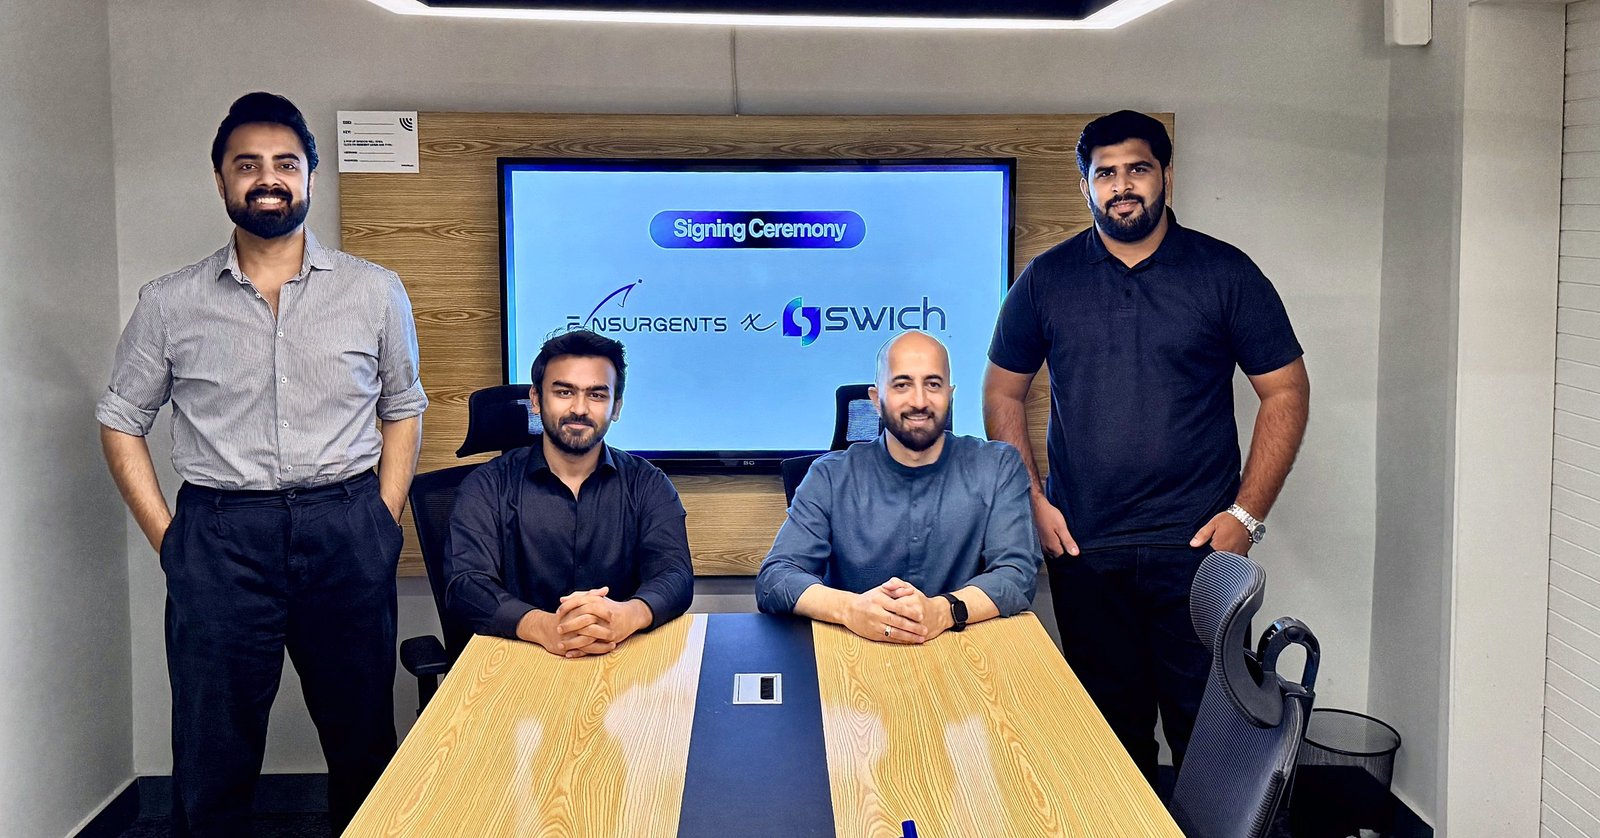
The moments our engagements become official — signed across the table with the teams we build alongside.